
Home / Modules / Finance & Accounts
One set of books for the whole institution, with every module posting into it.
Complete accounting for a School, College, University or Company: books, budgets, purchases, stores, assets, tax, statutory statements and the year-end close. Nothing is re-entered from fees or payroll, because the entries arrive in the ledger on their own.
One ledger, this month
From the opening balance to the year-end close, in nine steps.
Each step builds on the last. The books are set up once, and every later step reads from the same entries.
Set up the books
Chart of accounts, financial year, cost centres and the framework.
Record each day
Module entries arrive on their own; the rest are keyed as vouchers.
Buy and pay
From requisition to payment and the books.
Control the budget
Spent, committed and left, before anyone spends more.
Prove the money
Bank statements matched and control accounts certified.
Close the month
A checklist with tasks, owners and due dates.
Produce the statements
In the format the regulator asks for.
File the taxes
GST, TDS and the certificates, from the same books.
Close the year
Balances carried forward and the new year opened.
A purchase goes from request to books in eight steps, and each one is checked.
The order, the delivery and the invoice must agree before a payment is released.
Requisition
A department asks for an item.
Purchase order
Raised to a vendor, from the vendor list.
Goods received
Recorded against the order.
Supplier bill
Entered when the invoice arrives.
Three-way check
Order, delivery and invoice compared.
Approval
By the amount of the bill.
Payment
Released by treasury, with the bank advice.
Books
Posted to the ledger and the budget.
Every part of the accounts, from the first voucher to the audit.
Each block below covers one part of the finance work. Together they keep one set of books that the auditor can trust.
Every voucher balances, and every period closes and stays closed.
Vouchers use the institution's own numbering and must balance before they are saved. Financial periods close and lock, so a closed month cannot be changed quietly.
- Chart of accounts, voucher types with the institution's own numbering, and balanced vouchers.
- Financial periods that really close and lock.
- Cost centres and departments.
- Recurring entries for rent, maintenance contracts and subscriptions.
- Prepayments and revenue spread over time.
- Allocation of shared costs across departments.
- Supporting documents attached to every voucher and bill.
- A permanent audit trail: who changed what, and when, and it can never be erased.
Voucher, Hostel rent
Trial balance, this quarter
Every report comes from the entries, and an unusual entry raises its own alert.
The trial balance, day book, ledgers, cash and bank books are worked out from the entries themselves. A cash‑flow forecast and a variance analysis between periods show where the money is heading.
- Trial balance, day book, group summary, general and subsidiary ledgers, cash book and bank book.
- Receivables and payables ageing.
- Variance (flux) analysis between periods.
- Cash-flow forecast.
- Unusual‑entry (anomaly) alerts.
Statements in the format the regulator asks for, from the same books.
Six reporting frameworks are ready to use. The system suggests how each account maps to a statement line, and the accountant confirms it before the statement is produced.
- Balance sheet, income and expenditure, receipts and payments, with schedules and notes.
- Comparison with the previous period, and PDF and Excel export.
- XBRL-ready taxonomy filing.
Balance sheet, format
Budget, Science department
See what is spent, committed and left, before anyone spends more.
Every department has a budget. Spend is shown as it happens, including the orders still open, so a department is warned before it goes over.
- Budget heads and sub-heads, allocations, revisions and re-appropriation.
- Actual spend, committed spend (open purchase orders) and balance, live.
- A warning before a budget is exceeded.
Bills go to the right approver for their amount, and are paid in the right order.
Small bills go to the head of department, and large ones go up to the top approver. Retention money is held back and released in stages, and every payment goes out with a bank advice.
- 15 bill types, with supplier bank and tax profiles.
- Approval by amount: small bills go to the HOD, large ones up to the top.
- Retention money and staged release.
- Part payments, payment runs, treasury release and bank advice files.
- Cheque register and cheque printing.
- Debit and credit notes.
- The online payment gateway for each institution.
Bill, Lab equipment
Bank reconciliation, October
Prove the money: bank statements matched, and control accounts certified by three people.
Bank statements are imported and matched entry by entry. Control accounts are signed off by three people, so no single person can certify a balance alone.
- Bank statements uploaded and matched against the books.
- Control accounts certified by three people.
Purchases are matched to the order and the delivery, before a rupee is paid.
Vendors are kept without duplicates. Quotations are compared, and the lowest valid bid is picked. Stock is valued at its full landed cost, so freight and duty count.
- Vendors, with no duplicates, requisitions, purchase orders and goods received notes.
- Three-way match: order against delivery against invoice.
- Requests for quotation, sealed tenders, comparative statements and picking the lowest bid (L1).
- Rate contracts.
- Earnest money and security deposits register.
- Landed cost: freight and duty added into the stock value.
- Public procurement, through GeM in India.
Three-way match, PO 214
Stores register, lab consumables
Every item in the store is valued and counted against the books.
Receipts, issues, transfers and adjustments are recorded as they happen. The stores register matches the books, and a physical count is done blind, so the store keeper does not see the book figure while counting.
- Stores and items, with weighted-average valuation.
- Receipt, issue, transfer and adjustment.
- The stores register matched to the books.
- Physical verification with blind counting, write-offs and surplus under sanction.
- Dead-stock and reorder alerts.
- Goods movement documents, including e-way bills.
Every asset is on the register, depreciated, tagged and insured.
Each asset has a category, a useful life and a depreciation method. Depreciation is posted to the books each period, and the fixed asset schedule matches the ledger.
- An asset register with categories, useful life and depreciation methods.
- Depreciation runs posted to the books.
- A fixed asset schedule matched to the books.
- Disposal with gain or loss, revaluation, impairment and capital work in progress.
- Asset tagging with barcodes, and physical verification.
- An insurance register with renewal alerts.
- Leases under Ind AS 116.
- Maintenance due dates.
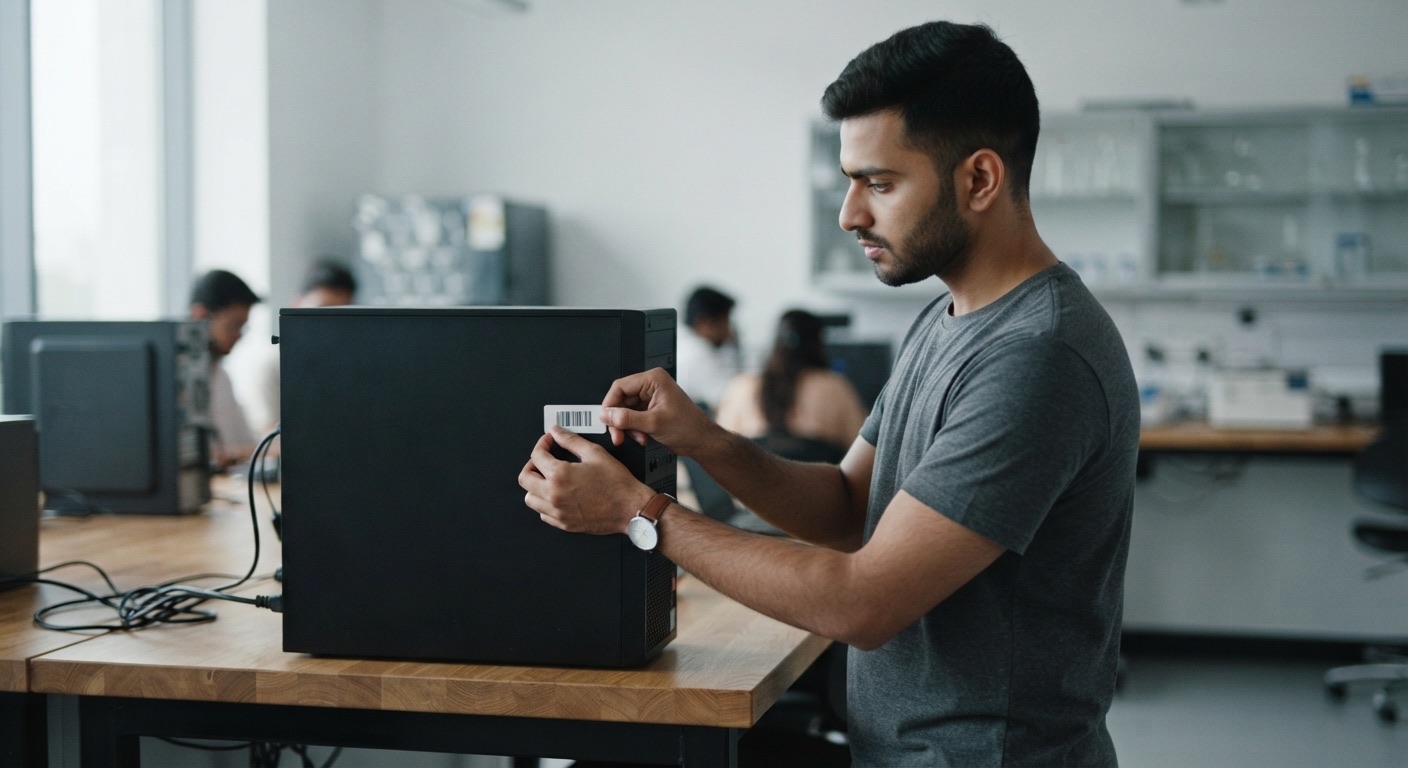
Asset, Lab computer 12
GST, this month
GST and TDS are filed from the same books, and the due dates are never missed.
Returns are prepared from the entries, input tax is matched against the supplier's filing, and each statutory due date appears on the compliance calendar.
- GST: returns (GSTR-1 and 3B), input tax matching (2B), HSN and SAC codes and e-invoices.
- TDS: deduction, returns (26Q and 27Q), Form 16A certificates and challan tracking.
- Other countries' taxes handled the same way: VAT in the UK and EU, and sales tax in the US.
- A compliance calendar of statutory due dates.
- Practice management for accounting firms: clients, a deadline board, document requests from clients, filing runs, and signing of returns.
Grants, endowments and public funds each keep their own ledger.
A grant gets its own ledger and its own utilisation certificate. Public funds drawn through the government's system are recorded against the scheme, and endowment and corpus funds are kept apart from the general fund.
- Grants and schemes, with a separate ledger and utilisation certificates.
- Public funds drawn through the government's system (PFMS in India).
- Endowment and corpus funds.
- An investment register.
- Consolidated accounts across Colleges and units, with inter-unit entries removed.
- Provisions and contingent liabilities.
- Multi-currency with exchange rates, revaluation and gain or loss.
- Treasury.
Grant, research project
Close checklist, October
The month closes on a checklist, and the year closes with a preview of what it will post.
Each task on the close list has an owner and a due date, and the sign-off is recorded. At year end the system shows what closing will post before it posts, then carries the balances forward and opens the new year.
- A month-end close checklist with owners, due dates and sign-off.
- Year-end close: a preview of what closing will post, carry-forward of balances, and the new year opened.
- Opening balances and migration from earlier systems, such as Tally.
Fees, payroll, hostel, admissions and research post into these books by themselves.
Each module records its own event, and the accounts take it from there. An accountant keys in only what no other module records, and the Tally export carries the books out when a partner needs them.
- Fees, payroll, pension, PF, hostel, admissions deposits, exam and document fees, research grants, legal bills, affiliation fees and assets all post into the books automatically.
- Tally export.
Entries posted this week
What sets the module apart from a shop's accounts.
Each of these is part of the module itself.
- Built for institutions, not just shops. UGC and ICAI formats, grants, endowments, utilisation certificates, and consolidation across Colleges.
- One set of books for the whole ERP. Nothing is re-entered from fees or payroll.
- World-ready. Tax, statements and currency follow the institution's country. India is one profile among several.
- Audit-ready. A permanent audit trail, attached proof, maker-checker approvals and three-person reconciliations.
- Honest numbers. Balances are always worked out from the entries themselves, never typed in.
Finance & Accounts takes entries from the modules around it.
The books are only complete when the other modules post their events. These are the ones that post most.
Built for the people who keep the books, approve the spend and audit the result.
Each role sees the part of the accounts that belongs to it.
Accountants
Record the day's entries, bills, receipts and bank reconciliation.
You want the books to balance without a second pass.
The finance manager or controller
Closes the month and year, and produces the statements.
You want the statements ready on the day they are due.
Store keepers and the purchase department
Raise requisitions and orders, record goods received, and keep stock.
You want stock and orders to agree with the books.
Approvers: HOD, registrar, finance officer, vice‑chancellor or director
Approve bills and purchases by amount.
You want to approve only what the rules say you should.
The treasury and the cashier
Release payments.
You want to pay only what is approved and matched.
Auditors
Read the books, the audit trail and the supporting documents.
You want every entry traceable to a document.
The management and trustees
See budgets, cash flow and the financial health of the institution.
You want the position in one view, without asking for it.
Questions people ask about Finance & Accounts.
What does the Finance & Accounts module do?
It keeps the complete accounts of an educational institution or a Company: the general ledger, budgets, purchasing, stores, fixed assets, tax, statutory statements and the year-end close. Every other module posts into it automatically.
Do fees and payroll have to be entered again in the accounts?
No. Fees, payroll, pension, PF, hostel income, admission deposits, exam and document fees, research grants, legal bills and affiliation fees all post into the books automatically. Accountants key in only what no other module records.
Which financial statement formats are supported?
Six reporting frameworks are ready: the UGC uniform format, the ICAI non-profit format, Schedule III, IFRS, US non-profit (ASC 958), and the UK further and higher education SORP. Each account is mapped to a statement line, and the accountant confirms the mapping.
How are bills approved?
By amount. Small bills go to the head of department, and large bills go up to the top approver. Purchase bills are matched against their order and delivery before they are paid.
Does it handle GST and TDS?
Yes. It prepares GSTR-1 and 3B returns, matches input tax against GSTR-2B, and issues e-invoices. For TDS it prepares the 26Q and 27Q returns and Form 16A certificates, and tracks challan payments from the same books.
Can an entry in the books be erased later?
No. The audit trail is permanent. It records who changed what and when, and it cannot be erased.